Budgeting
How To Create A Realistic Budget After Divorce
Build a post-divorce budget around your actual income, fixed obligations, changing household costs, and the priorities that matter most in your new financial life.
Read ArticleFINANCES
Build a realistic budget, improve your cash flow, and create financial breathing room after divorce.
Browse the ArticlesFINANCES
Build a realistic budget, improve your cash flow, and create financial breathing room after divorce.
Browse the Articles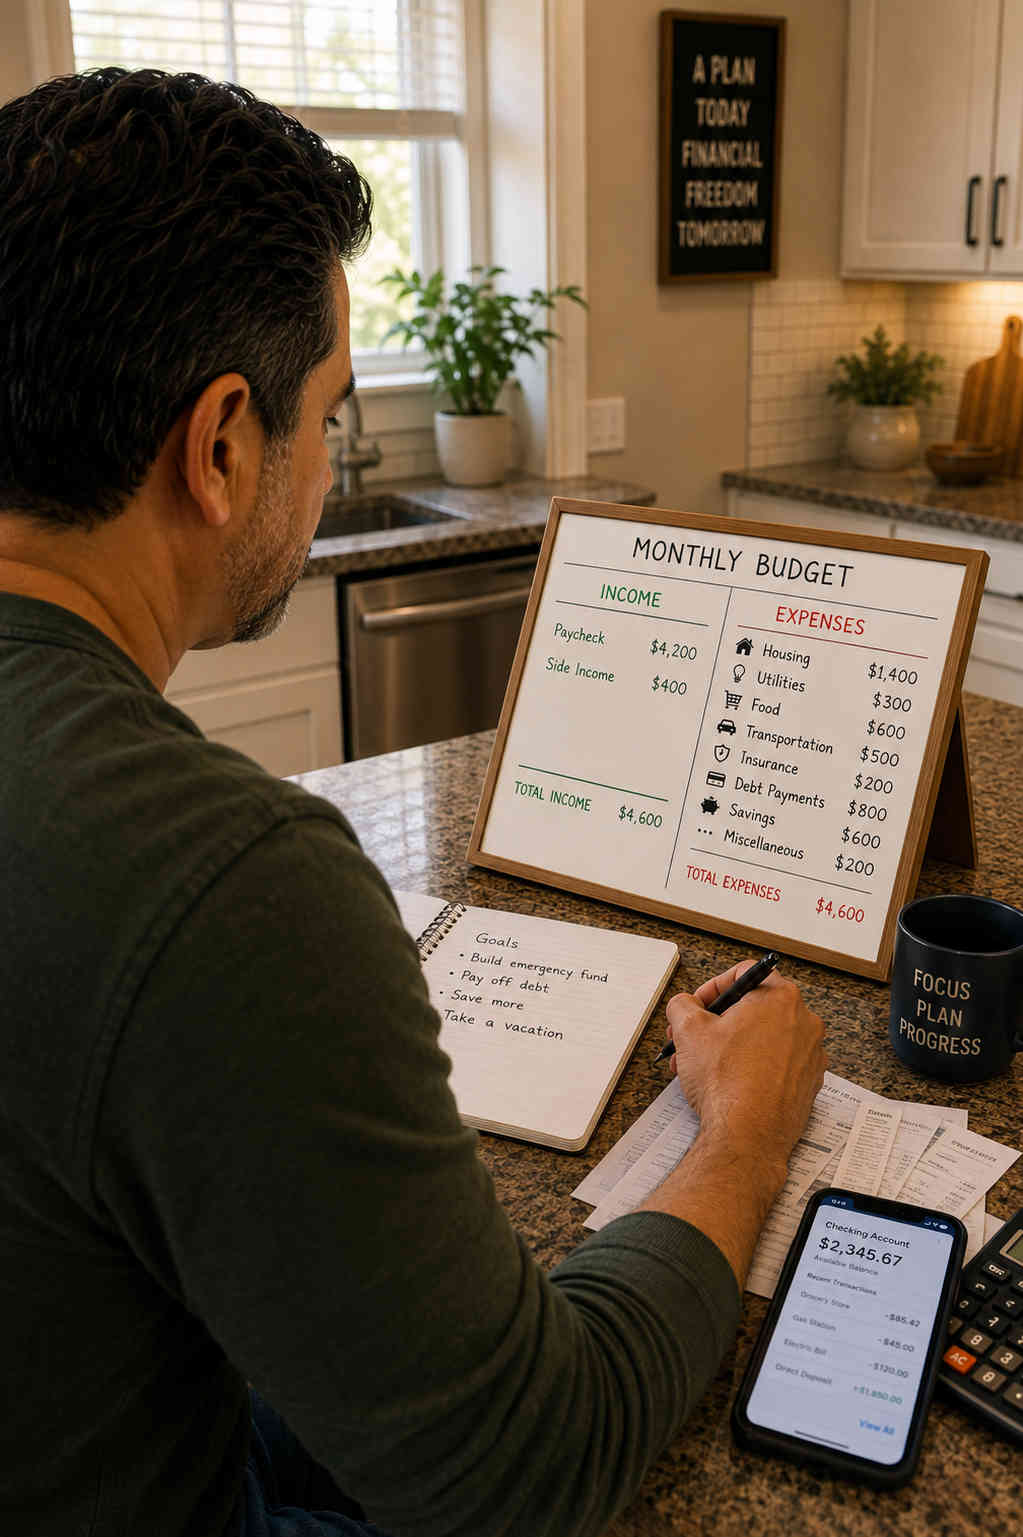
After divorce, your income and expenses may look very different. Explore practical guides to manage everyday spending, prepare for unexpected costs, and build a stronger financial foundation one month at a time.
Budgeting & Cash Flow Articles
Start with these practical guides for budgeting, cash flow, emergency savings, and knowing when you are financially ready to invest. Another Budgeting & Cash Flow article will be added here in the future.
Build a post-divorce budget around your actual income, fixed obligations, changing household costs, and the priorities that matter most in your new financial life.
Read Article
Learn how to find the cash-flow squeeze, smooth out bill timing, reduce recurring pressure, and begin building a margin between what you earn and what you spend.
Read Article
Create a practical cash reserve even when money is tight, choose a realistic first savings target, and reduce the chance that unexpected expenses become new debt.
Read Article
Learn how much financial cushion you should have before investing, including emergency savings, monthly cash flow, and the ability to handle unexpected expenses without disrupting your investments.
Read ArticleThis space is reserved for a future article.
Build Financial Breathing Room
These areas can help you turn a tighter post-divorce financial picture into a plan that becomes more stable, predictable, and manageable over time.
Base your plan on actual take-home income and current expenses, then decide in advance how much is available for necessities, savings, debt, and discretionary spending.
Find the recurring expenses, timing problems, and spending leaks that keep your checking account under pressure even when your income appears sufficient on paper.
Create room for car repairs, medical bills, school costs, home expenses, travel, and other irregular costs so they do not automatically become credit-card debt.
You do not have to rebuild your finances all at once. Use these guides to get the monthly basics under control first, then create more room for saving, debt reduction, and longer-term goals.
A stronger post-divorce financial life is usually built through ordinary monthly decisions: keeping essential expenses manageable, planning ahead for uneven costs, maintaining a cash cushion, and giving yourself enough margin to recover from mistakes without falling deeper into debt.
Back To Finances