Your Five-Year Recovery
Divorce Changed The Numbers. It Does Not Have To Decide Your Future.
After divorce, financial recovery can feel less like building wealth and more like trying to stop a leak. There may be a new mortgage or rent payment, legal bills, support obligations, divided retirement accounts, duplicated household expenses, credit-card balances, and the uncomfortable realization that the financial plan you once had no longer exists.
That is why the first goal is not to become rich. It is to become stable. Then you build from stability toward strength, and from strength toward freedom.
Five years is long enough for consistent financial decisions to produce a dramatically different life, but short enough to make the plan feel real. You do not need to fix everything this month. You need to know what comes first, what comes next, and what you are building toward.
First, Find Out Exactly Where You Stand
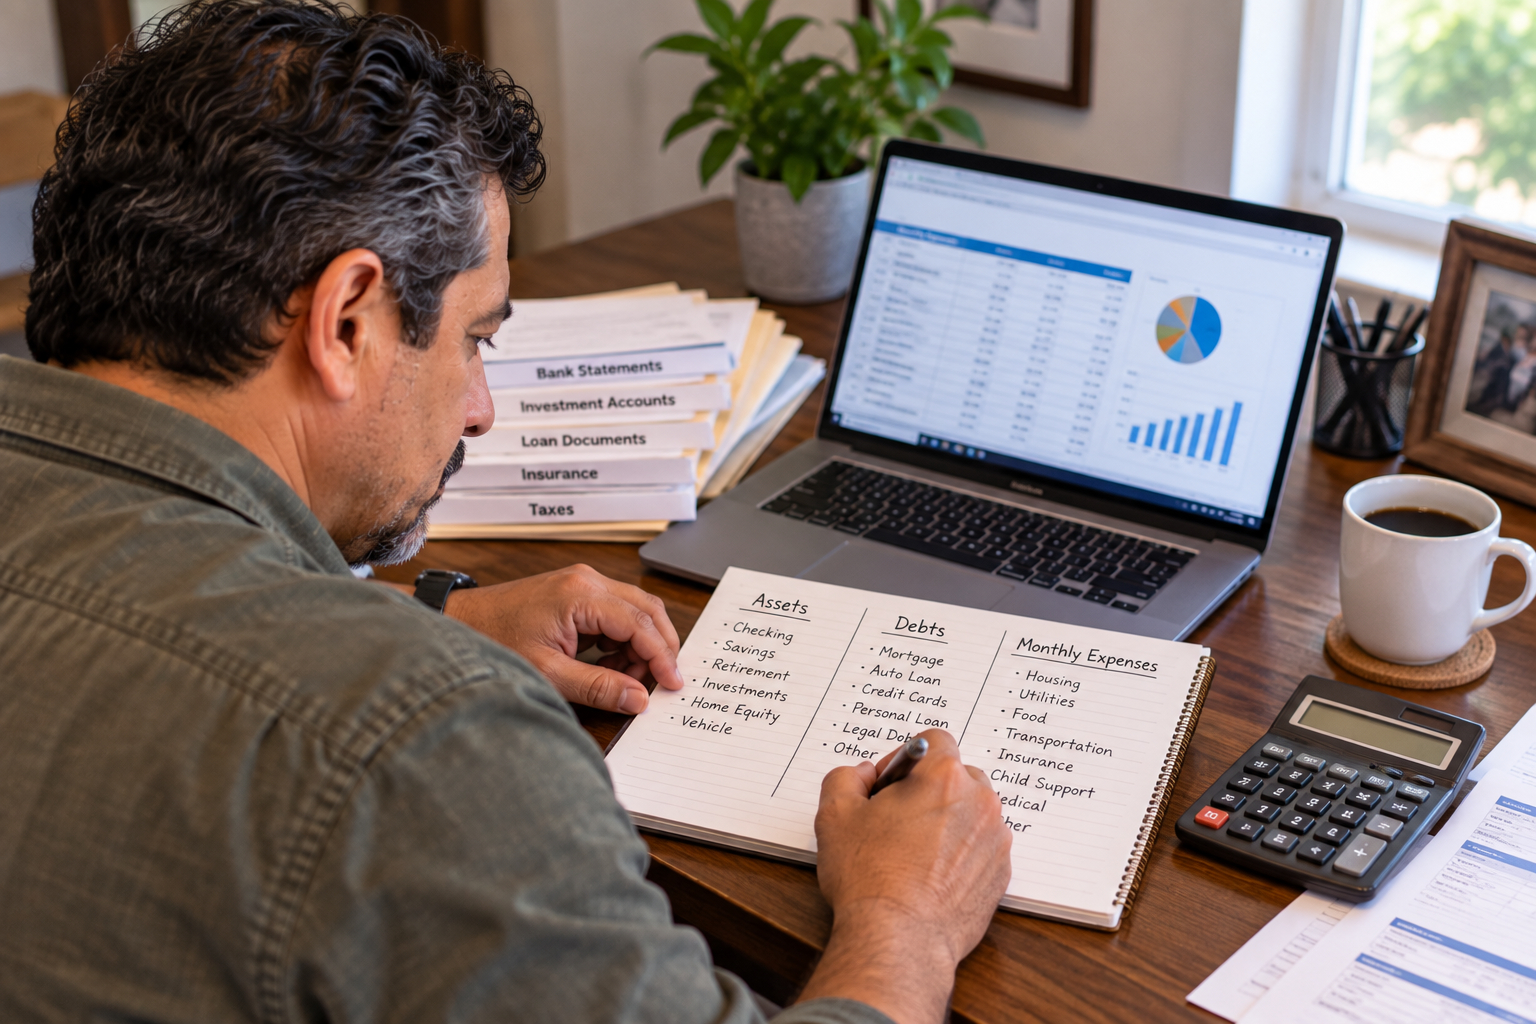
Before you create a five-year plan, get the entire financial picture onto one page. Avoid estimating from memory. Pull the statements and write down the actual numbers.
List checking and savings balances, retirement accounts, investments, home equity, vehicles and other meaningful assets. Then list every debt: mortgage, auto loan, credit cards, personal loans, tax balances and any divorce-related obligations. Finally, calculate your true monthly spending.
Your net worth may be lower than it was before the divorce. That number is not a verdict. It is simply the starting coordinate on the map.
Your Starting-Point Checklist
- Calculate current net worth: assets minus debts.
- List every monthly fixed obligation.
- Review the previous three months of variable spending.
- Identify high-interest debt and its interest rate.
- Record retirement and investment balances.
- Identify irregular expenses that will occur during the next twelve months.
- Determine how much cash you have available for emergencies.
Year 1: Stabilize And Stop The Financial Bleeding
The first year after divorce should be defensive. Your job is to make the new household sustainable. That may require decisions that feel like a step backward: driving the same car longer, living in a smaller place, delaying travel, cutting subscriptions, eating out less, or saying no to purchases that once felt routine.
Do not build your post-divorce budget around the lifestyle you had while married. Build it around the income and responsibilities you have now.
Start with the expenses that can hurt you fastest. Make minimum payments on every debt, attack high-interest balances, get current on taxes and insurance, and stop adding new consumer debt. If cash flow is negative, investing more aggressively is not the immediate priority. Fix the leak first.
At the same time, create a small emergency reserve. Even $1,000 to $2,000 between you and the next car repair can prevent an unexpected expense from returning to a credit card.
Build The Emergency Fund Before Life Tests You Again
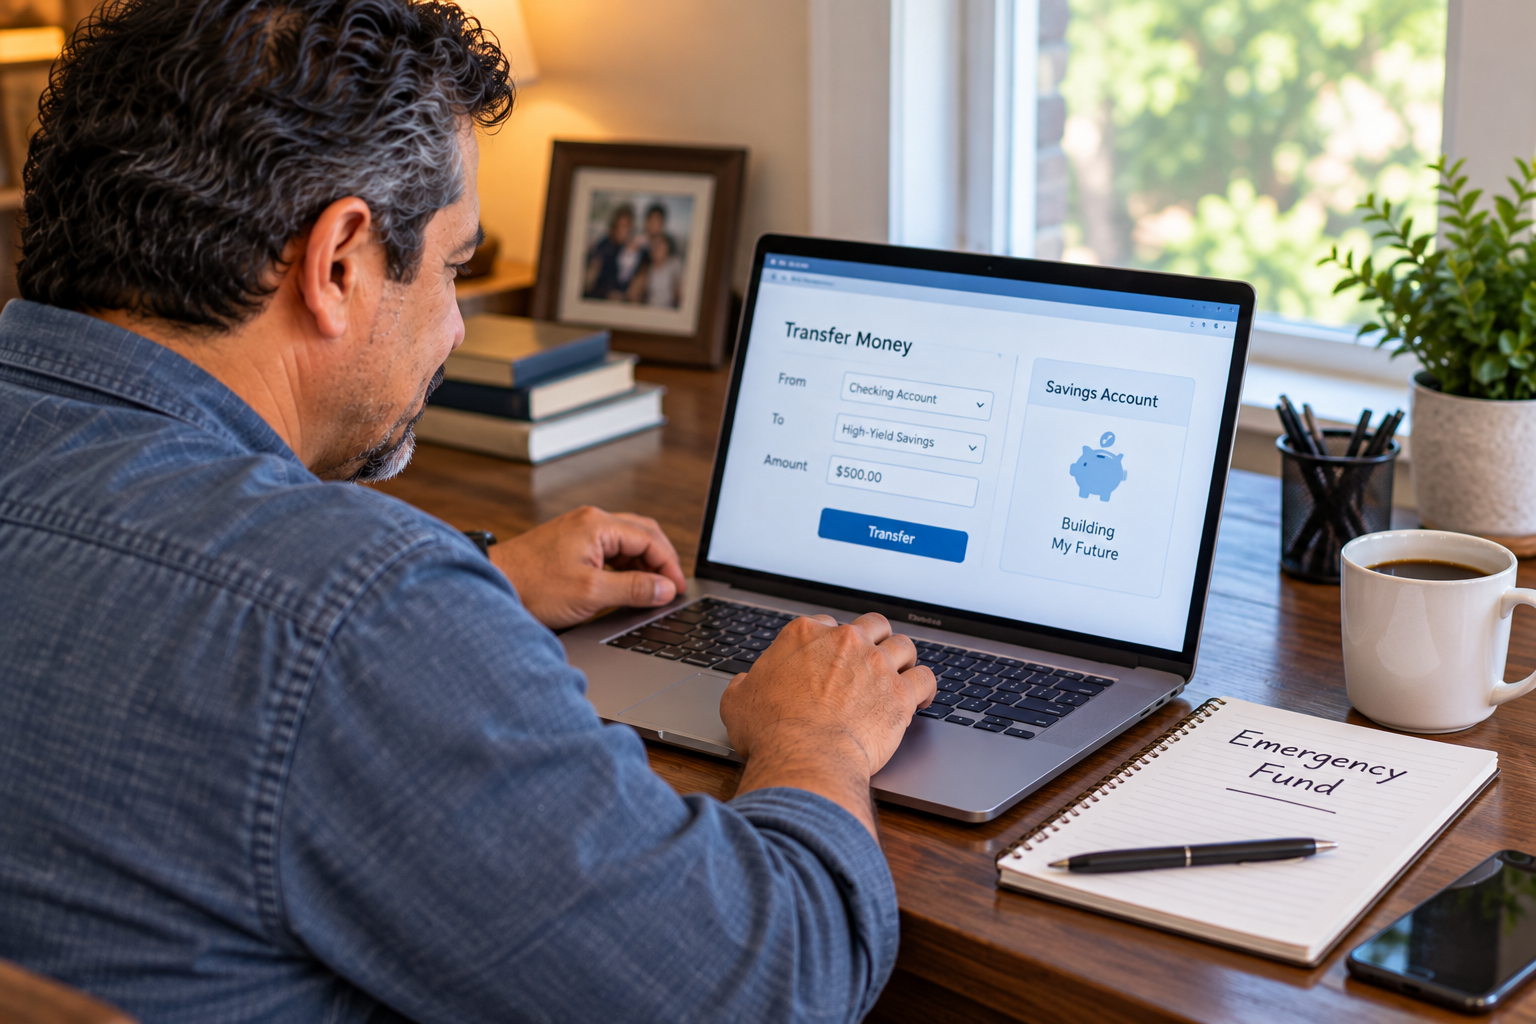
Once the monthly budget is under control, expand the emergency fund. A useful long-term target is several months of essential expenses, but do not let the size of that goal keep you from beginning.
Automate a transfer every payday. Treat emergency savings like a bill owed to your future self. Keep it separate from the account used for ordinary spending so it does not quietly become vacation money, furniture money, or a convenient source for impulse purchases.
Financial security after divorce is partly about return on investment, but it is also about resilience. Cash reserves give you options when employment changes, a major repair appears, or a family responsibility arrives without warning.
Year 2: Build A Financial Foundation That Can Carry More Weight
By the second year, the goal shifts from stopping damage to building capacity. Increase the emergency reserve, continue eliminating expensive debt, and create sinking funds for costs you know are coming.
Car repairs, insurance premiums, home maintenance, holidays, school expenses and medical deductibles are not true emergencies when they happen regularly. Divide the expected annual cost by twelve and save a little each month.
This is also the time to restore retirement contributions if they were reduced during the divorce. If your employer offers a retirement match, understand the plan and take advantage of the match when your cash flow allows it. Then increase contributions gradually rather than waiting for the perfect moment.
Year two may not look exciting from the outside. That is fine. Financial foundations are mostly invisible. The evidence is that fewer expenses surprise you, debt balances are falling, savings are rising, and you no longer feel that one bad month could knock everything over.
Year 3: Move From Recovery To Building Wealth
Year three is where the plan should begin to feel different. High-interest debt may be gone or substantially reduced. Your emergency fund should be stronger. Cash flow should be more predictable. Now more of your money can be assigned to long-term growth.
Increase retirement contributions. Consider diversified investing appropriate to your time horizon and risk tolerance. If divorce reduced your retirement balance, resist the temptation to make up for lost time by taking reckless risks. Recovery is built by contribution rate, time, diversification and consistency—not by finding one investment that supposedly fixes everything.
Set a specific annual savings and investing target. Measure progress by dollars contributed and net worth, not by whether markets happened to rise that month.
This is also a good point to get professional help when your situation warrants it. A qualified financial professional can help you evaluate retirement projections, taxes, investment allocation and competing priorities. The goal is not to hand over responsibility. It is to make better decisions with clearer information.
Increase Income Instead Of Trying To Cut Your Way To Freedom
Expense control matters, especially early in recovery, but there is a floor beneath which your lifestyle cannot realistically fall. Income has more room to grow.
Ask what could increase your earning power over the next two years. That might mean negotiating compensation, earning a certification, changing employers, learning a valuable skill, taking on selective freelance work, or building a side business that does not jeopardize your primary income.
When income rises, avoid immediately upgrading the lifestyle. Direct a meaningful percentage of each raise, bonus or side-income dollar toward debt reduction, retirement and investments. This is how a higher income turns into higher net worth instead of simply more expensive monthly obligations.
Year 4: Protect What You Have Rebuilt
As your financial position improves, protection becomes more important. Review insurance coverage, beneficiaries, estate documents and the people authorized to make financial or medical decisions if you cannot.
Divorce can leave outdated beneficiary designations, old assumptions in wills, and insurance coverage designed for a household that no longer exists. Review these items deliberately and use qualified legal, tax or insurance professionals where appropriate.
Protection also means avoiding a second financial collapse caused by lifestyle inflation, inadequate insurance, concentrated investments, or financial decisions made to impress someone else. You have spent several years rebuilding. Do not expose the new foundation to risks you do not need to take.
Make Housing Serve The Plan
Housing is often the largest financial decision after divorce. It is also one of the easiest places to let emotion override mathematics.
You may feel pressure to replace the old family home, provide a certain image for your children, or prove that divorce did not lower your standard of living. None of those feelings should determine how much house you buy.
Evaluate the total cost: mortgage or rent, taxes, insurance, utilities, maintenance, commuting and the amount of cash the property prevents you from saving elsewhere. A smaller home that allows you to invest, travel, handle emergencies and sleep well can be a far better financial decision than a larger home that keeps you permanently stretched.
Year 5: Turn Financial Strength Into Financial Freedom
Financial freedom does not necessarily mean you never have to work again. For a man rebuilding after divorce, it can mean something more immediate and useful: your monthly life is no longer controlled by financial emergencies and old obligations.
By year five, you want a strong cash reserve, manageable or eliminated consumer debt, consistent retirement contributions, a growing investment balance, housing you can comfortably afford, and enough monthly margin to make choices without panic.
That margin changes the way life feels. You can absorb a repair. You can help a child without putting the expense on a credit card. You can consider a job change without wondering whether missing one paycheck will wreck the household. You can take a trip because the money was saved in advance. You can say no to work, purchases, or relationships that require you to betray the financial stability you rebuilt.
A Simple Five-Year Roadmap
Year 1 — Stabilize: Build the new budget, stop new debt, attack high-interest balances, and create the first emergency reserve.
Year 2 — Foundation: Expand emergency savings, prepare for predictable expenses, and restore retirement contributions.
Year 3 — Build: Increase investing, rebuild retirement assets, raise income, and track net-worth growth.
Year 4 — Protect: Review insurance, beneficiaries, estate planning, taxes and major risks.
Year 5 — Freedom: Strengthen investments, preserve margin, make housing fit the plan, and use financial stability to create more choices.
What The Numbers Could Look Like After Five Years
The exact amounts will depend on your income, age, divorce settlement, debt and starting assets, so the goal is not to copy someone else's numbers. The point is to understand what repeated monthly decisions can do.
A man who frees up $750 a month during the first year and eventually raises that amount to $1,500 a month for saving, debt reduction and investing can direct tens of thousands of dollars toward his future over five years. Add employer retirement contributions, investment growth, debt interest avoided, raises and bonuses, and the difference between year one and year five can become substantial.
The transformation is not created by one brilliant financial move. It is created by hundreds of ordinary decisions that point in the same direction.
Do Not Compare Your Year One To Someone Else's Year Twenty
Divorce can create a particularly painful kind of financial comparison. Friends may still be living in two-income households. Coworkers may be talking about vacation homes or early retirement while you are rebuilding an emergency fund. Your former spouse's financial situation may appear better than yours.
Comparison does not improve the math. Your job is to improve your own position from one quarter to the next and one year to the next.
Track a few numbers: net worth, consumer debt, emergency savings, retirement balance, annual investment contributions and the percentage of income required for fixed expenses. Those numbers will tell you whether the plan is working.
Financial Freedom Is Really About Options
Money matters because of what it allows you to handle and what it allows you to refuse. A man with no savings may have to stay in a job he hates, borrow when the car breaks, or tolerate a financial emergency that controls his entire month.
A man with reserves, low debt and growing investments has options. He can make decisions from strength instead of desperation.
That is the deeper purpose of financial recovery after divorce. You are not trying to recreate the exact balance sheet you had before the marriage ended. You are building a financial life that is durable enough to support the man you are becoming.
Five Years From Now Is Coming Anyway
Five years can sound like a long time when you are standing in the financial wreckage of a divorce. But those years will pass whether you have a plan or not.
You do not need to recover everything this year. You need to make this year better than the last one. Stabilize first. Build the foundation. Restore your ability to save. Increase your income. Invest consistently. Protect what you rebuild. Keep housing and lifestyle decisions aligned with the future instead of the past.
At some point, you will notice that money no longer produces the same anxiety. Bills are handled. Savings exist. Debt is smaller. Retirement is moving in the right direction. The next unexpected expense is inconvenient rather than catastrophic.
That is when financial recovery becomes something more than recovery. It becomes freedom.
You don't have to win your old life back. You need to build the next one.
The Five-Year Rule
Build In The Right Order
Stability before lifestyle. Emergency savings before unnecessary risk. High-interest debt before aggressive investing. Consistency before complexity. Protection after progress. Freedom comes from giving each dollar a job that supports the life you are building next.