Turning 50 with very little money can be frightening. After divorce, the home you helped pay for may be gone, retirement accounts may have been divided, and the monthly bills may look nothing like they did when you were married. You may feel as if you have fifteen years to recover from thirty years of financial decisions.
The good news is that fifteen years is still a meaningful amount of time. The difficult news is that there is no magic investment, shortcut, or guaranteed return that will make up for lost savings. Financial security will come from a series of ordinary decisions made consistently: spending less than you earn, controlling debt, protecting your income, and investing with a plan.
Consider Mike, a divorced man who reaches 50 with modest savings, debt, and a smaller place to live. His story is an illustration, not a promise. His goal is not to become a millionaire overnight. It is to reach 65 with manageable expenses, a dependable retirement plan, and choices he did not have at 50.
First, Redefine What Financially Secure at 65 Means
Financial security does not have one dollar amount. A man who owns an affordable home, has little debt, and needs $3,000 a month may require less investment income than someone who earns more but carries a large mortgage and car payments. The starting point is the life you will need to fund, not a headline about how much everyone should have saved.
Write down your projected essential expenses at 65: housing, utilities, groceries, transportation, insurance, health care, taxes, and basic recreation. Then estimate dependable income sources such as Social Security and any pension. The gap between income and expenses is what your savings and investments must help cover. Inflation, health costs, taxes, and investment risk all matter, so revisit the numbers each year.
Ages 50–52: Stop the Financial Bleeding
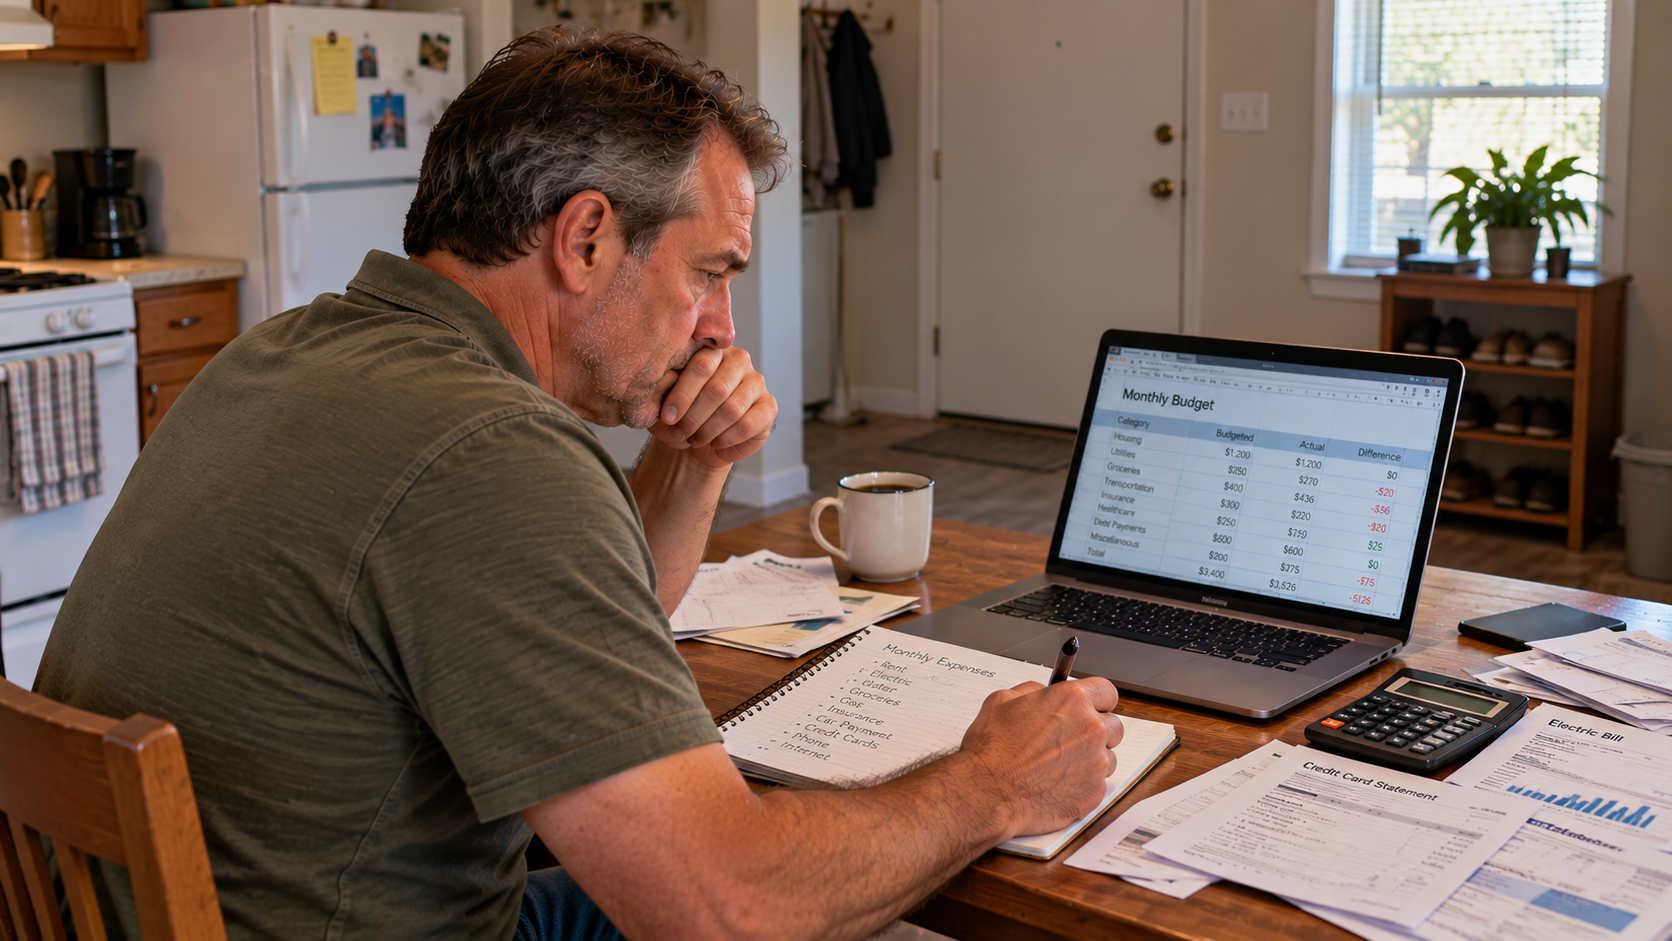
Mike’s first objective is stability, not growth. Before he thinks about investments, he needs to know where every dollar is going. He lists his take-home pay, court-ordered obligations, minimum debt payments, housing costs, insurance, and recurring subscriptions. He also lists every account balance and interest rate.
A budget is not punishment. It is a way to prevent a difficult financial season from turning into a permanent one. If the budget does not balance, he must make changes now—whether that means negotiating bills, changing housing, reducing discretionary spending, or increasing income.
Step 1: Build a Budget You Can Actually Live With
Start with necessities, required payments, and a small allowance for ordinary life. A budget that eliminates every pleasure usually collapses. Track spending for at least one full month, then assign each dollar a job. Set automatic payments where practical, and check balances weekly to catch problems before overdraft fees or late payments appear.
Step 2: Create a Starter Emergency Fund
Unexpected repairs and medical bills can send a recovering man back into credit-card debt. Begin with a manageable cash cushion—perhaps $1,000 or one month of essential expenses, depending on your circumstances—then build toward several months of necessities. Keep emergency savings in an accessible, insured account rather than an investment that might fall sharply when you need the money.
Step 3: Attack High-Interest Debt
Credit-card interest can consume money that should be funding retirement. Pay required minimums on all accounts, then direct extra money toward the highest-interest balance, or use the smallest-balance method if early wins will keep you motivated. Avoid taking on new balances while you pay down old ones. If debt is unmanageable, a reputable nonprofit credit counselor may help you evaluate options.
Step 4: Protect the Income You Have
Health coverage, adequate insurance, a reliable vehicle, and an up-to-date estate plan are part of financial recovery. An illness, accident, or preventable legal problem can undo years of progress. Check beneficiaries after divorce, review your credit reports, and make sure you understand any continuing support obligations.
Ages 52–55: Turn Cash Flow Into Wealth
Once Mike has reduced expensive debt and created a savings cushion, his financial plan changes. The money that used to go to interest payments can now go to retirement contributions. He starts with his workplace retirement plan, especially any available employer match, then reviews IRA options and other accounts suited to his circumstances.
Step 5: Don’t Buy the “Recovery Car”
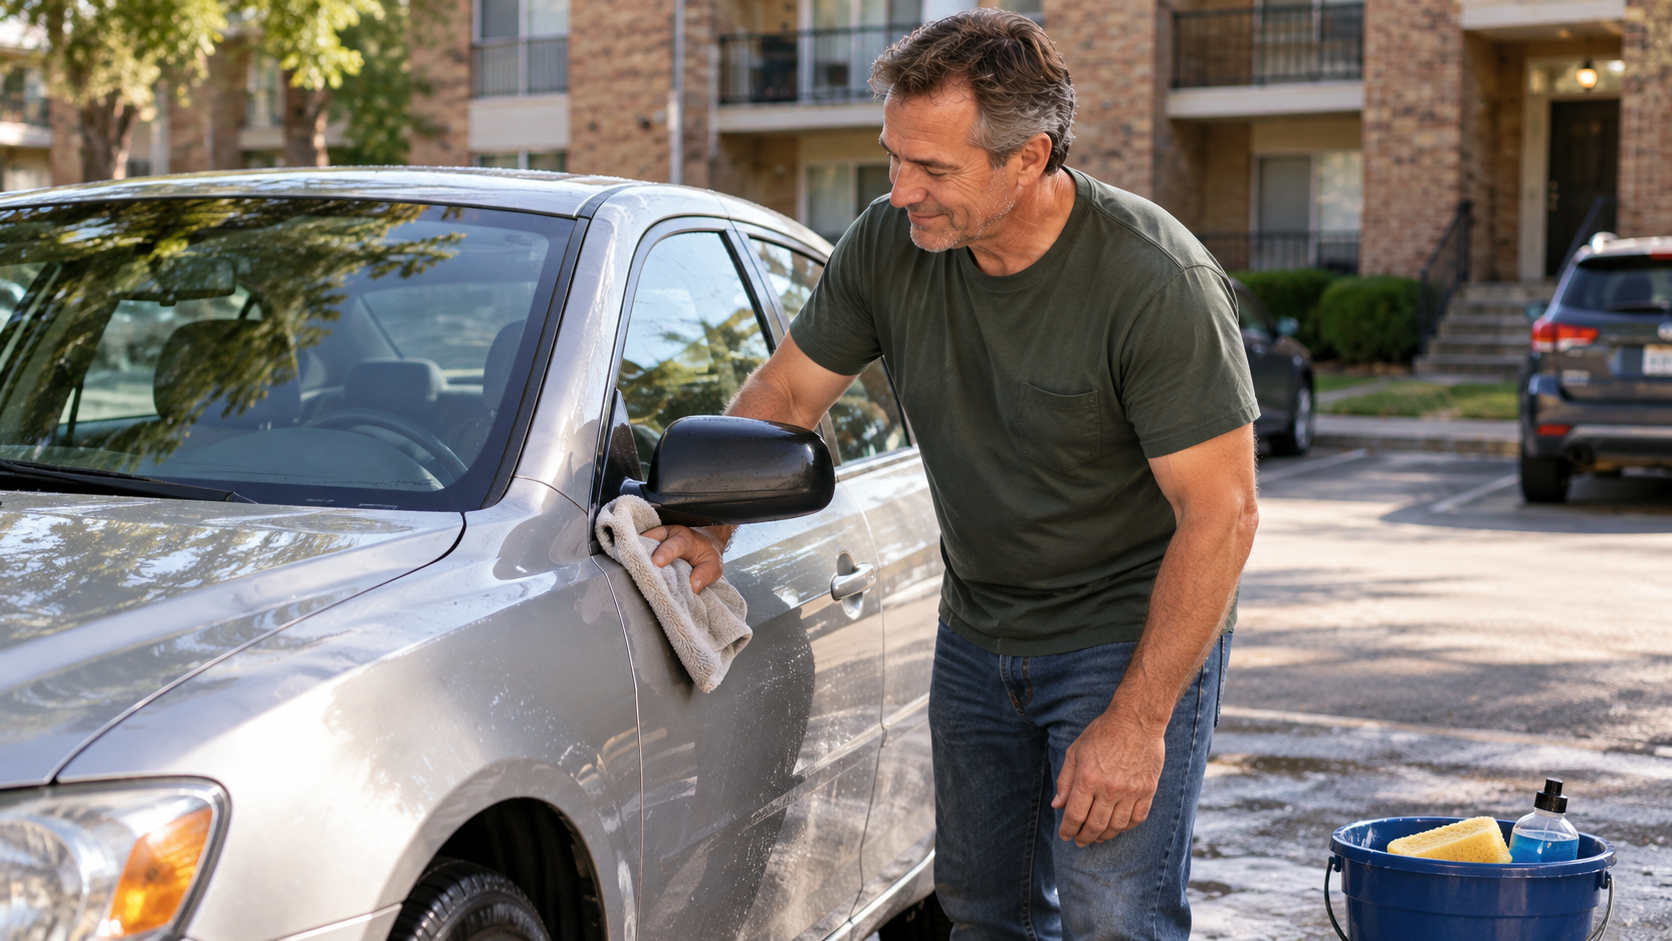
After divorce, it can be tempting to buy something that announces you are doing well. A large vehicle payment can quietly cost years of investment contributions. If Mike’s older car is safe and dependable, maintaining it may be a better decision than replacing it. He compares the total cost of ownership, not just the monthly payment.
Step 6: Increase Retirement Contributions Automatically
Retirement accounts offer tax advantages, and many workplace plans permit additional catch-up contributions for eligible savers over 50. Contribution limits and special age-based rules change, so check the current IRS limits and your plan’s terms rather than relying on old numbers. If Mike receives a raise, he directs part of it toward retirement before increasing his lifestyle.
He also avoids chasing spectacular returns. A diversified portfolio appropriate to his risk tolerance, time horizon, and retirement needs is generally more useful than gambling on one stock or speculative asset. The objective is to remain invested through ordinary market cycles without taking risks that could derail retirement.
Your 50s May Be Your Best Earning Years
Expense cuts have limits. Income growth can expand the amount available for debt reduction and savings. Mike asks which skills his employer values, what credentials could improve his pay, and whether changing positions or employers makes financial sense. He keeps his resume current and maintains professional relationships.
Side work can help, but only if the pay justifies the time, taxes, equipment, and stress. He avoids expensive business ventures built on unrealistic promises. He wants a reliable increase in net income, not another obligation that drains cash.
Ages 55–60: Build Momentum Without Increasing Your Lifestyle
By his late 50s, Mike may be earning more and carrying less debt. This is where many people accidentally stall. The new income becomes a bigger house, nicer car, costly vacations, and subscriptions that slowly fill the budget again. Instead, he establishes a rule: increases in income should first strengthen his financial position.
He raises retirement contributions when affordable, reviews his investments at regular intervals, and checks whether his projected retirement spending still makes sense. He also plans for larger irregular expenses, including vehicle replacement, home repairs, and family needs. A good plan accounts for these costs before they arrive.
Don’t Let Housing Destroy the Plan
Housing is often the largest retirement expense. Mike does not have to own a house to be financially secure, and renting may remain the right choice. If he buys, he evaluates the entire monthly cost: principal, interest, taxes, insurance, maintenance, utilities, and any association fees. He does not use the maximum mortgage a lender will approve as his budget.
An affordable home should support the retirement plan, not replace it. If purchasing would stop his retirement contributions or leave him without emergency savings, the timing or price may be wrong.
Ages 60–63: Protect What You Have Built
The closer Mike gets to retirement, the more important it becomes to understand his exposure to market declines. That does not necessarily mean abandoning stocks; it means having an allocation, cash reserves, and withdrawal plan that match his needs. He reviews investment fees, account beneficiaries, and the tax consequences of different withdrawal choices.
He also studies his Social Security benefit estimates at different claiming ages. Starting benefits at 62 generally produces a smaller monthly amount than waiting until full retirement age, while delaying beyond full retirement age can increase the benefit up to age 70. The right decision depends on health, earnings, family circumstances, and available savings. Medicare eligibility commonly begins at 65, but enrollment timing and coverage choices require planning.
Be Careful About Becoming Everyone’s Bank
Mike wants to help his adult son, but he has learned that a promise made out of guilt can threaten years of progress. He can be generous within a budget, offer practical help, or contribute a limited amount without taking on debts he cannot afford. He is honest about what he can and cannot do.
This is not selfishness. Financially secure parents may be better able to provide occasional help later than parents who exhaust their retirement savings today.
Ages 63–65: Turn Savings Into a Retirement Plan
A retirement date is not a complete plan. Mike estimates what he will spend, which income sources will arrive and when, how much cash he needs for near-term expenses, and how he will handle a bad market year. He considers whether part-time work would improve his options and how taxes could affect withdrawals from different accounts.
He stress-tests the plan: What if he needs a new roof? What if investments decline early in retirement? What if health costs are higher than expected? What if he lives to 90 or beyond? A qualified fiduciary financial planner can help evaluate these scenarios, particularly if pensions, divorce-related retirement orders, or complex taxes are involved.
The Fifteen-Year Roadmap at a Glance
What If You Are Starting With Almost Nothing?
You may not be able to save the amount financial articles recommend. Start with the amount your actual budget permits and increase it whenever circumstances improve. A later retirement date, part-time work, lower housing expenses, and realistic spending expectations may all be part of the solution. None of those choices is a personal failure.
If you are facing severe debt, limited employment options, or health problems, the timeline may be longer than fifteen years. Financial security is a direction and a set of protections, not a guarantee tied to one birthday. Avoid anyone who promises you can recover lost decades through a risk-free investment or a secret strategy.
Fifteen Years From Now Is Coming Anyway
At 50, Mike worried that his financial future had already been decided. At 65, he has not necessarily become wealthy. He has become deliberate. His bills are manageable, he understands his retirement income, and he has built habits that make financial surprises less frightening.
The transformation was not one brilliant investment. It was the budget he followed when nobody was watching, the older car he kept, the raises he saved, the debt he paid, and the boundaries he maintained. Those decisions added up.
Final Thoughts: Start With the Next Right Decision
If you are starting over financially after divorce at 50, you do not need a perfect fifteen-year forecast before you begin. You need an accurate picture of today, one achievable improvement this month, and a system for repeating useful decisions. Update the plan as your circumstances change.
Fifteen years from now, you will be 65 regardless of whether you begin today. Give your future self a better set of choices by taking control of the money you have now.